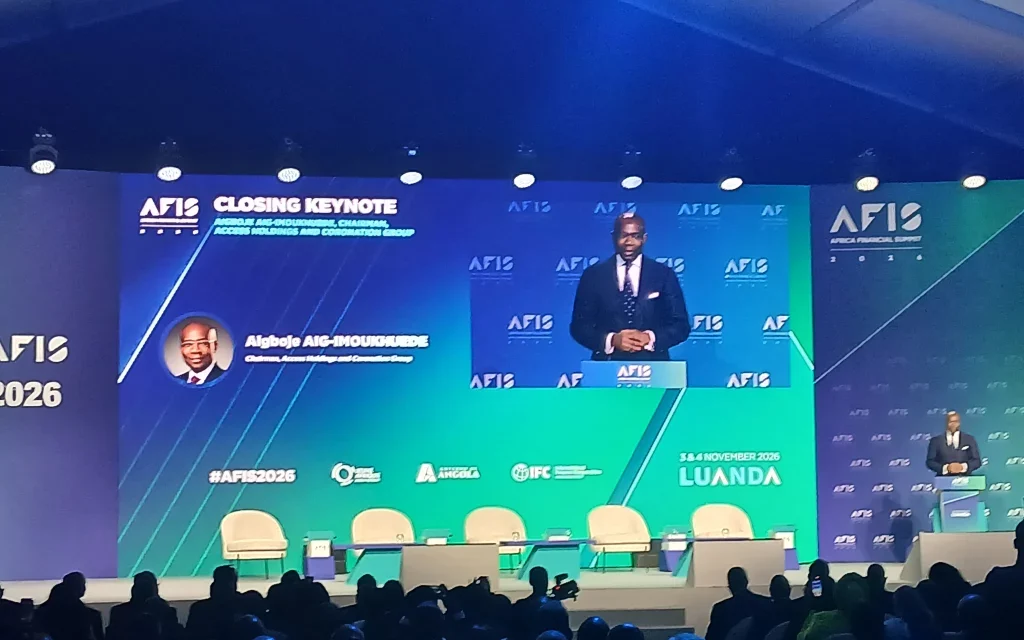
Aigboje Aig-Imoukhuede, chairman of Nigerian tier-1 lender Access Bank Group and monetary providers holding firm Coronation Group, argues that African monetary establishments must transfer past monetary stability to productive finance, unlock capital tied up in industrial transactions and construct banking techniques able to working throughout borders.
Africa’s monetary establishments have spent years debating the supply and price of capital. However, Aig-Imoukhuede believes the continent is asking the incorrect query.
Rather than focusing totally on how a lot capital Africa can entice, he needs policymakers and monetary establishments to look at how successfully the cash already accessible is being deployed.
“At this particular moment in Africa’s development, I believe the more important question is: How do we make better use of the capital we already have?” he mentioned through the closing session of the Africa Financial Industry Summit (AFIS) in Luanda, Angola.
His argument is that the continent’s monetary techniques must grow to be higher at connecting present capital to companies, productive financial exercise and long-term investments. Without that shift, monetary stability and stronger banking establishments might not translate into the broader financial prosperity Africa wants.
Aig-Imoukhuede outlined three priorities for attaining this: unlocking capital trapped in industrial transactions, mobilising long-term financial savings for long-term investments, and addressing authorities borrowing that limits the non-public sector’s entry to financing.
The cash trapped in industrial transactions
One of the largest alternatives, in his view, lies within the financing of small and medium-sized enterprises (SMEs).
Across Africa, companies generate vital financial worth by manufacturing and industrial actions, usually in cycles lasting 90 to 120 days. Yet smaller companies that offer items and providers to bigger corporations incessantly wrestle to entry financing.
A provider might fulfil an order for a giant company and file a credible industrial transaction on its books, but nonetheless face liquidity constraints as a result of its personal credit score profile is weaker than the customer’s.
Aig-Imoukhuede believes monetary establishments ought to change how they assess such transactions.
“When an SME supplies goods or services to a creditworthy buyer, that transaction should enable the SME to access financing at a rate that reflects the creditworthiness of the buyer, rather than the weaker credit profile of the small supplier,” he mentioned.
In impact, the industrial transaction itself might grow to be the idea for accessing credit score, permitting smaller companies to profit from the monetary energy of the bigger corporations they provide.
He pointed to digital invoicing for instance of the infrastructure that would make this potential, citing greater than three billion registered invoices in India, following the introduction of digital invoicing a decade in the past, and roughly 60 billion in Brazil.
He argued that Africa might unlock vital financial worth by creating comparable techniques, significantly given the continent’s giant inhabitants of SMEs and sole merchants.
The proposal requires central banks, industrial banks and different monetary establishments to rethink how they assess creditworthiness. Instead of relying totally on the monetary standing of particular person small companies, lenders might use verified industrial transactions and the customer’s energy to assist financing.
That would handle a persistent constraint for smaller suppliers: the hole between producing income and receiving cost.
Why long-term initiatives want long-term cash
A second precedence is mobilising financial savings for investments that require longer financing phrases.
Aig-Imoukhuede argued that banks can not proceed to rely closely on deposits that clients can withdraw at brief discover to finance initiatives requiring capital over 20 years.
“We cannot continue to rely on bank deposits, which can be withdrawn tomorrow, to finance long-term projects that require 20-year money,” he mentioned.
He believes there’s an urge for food amongst Africans for longer-term financial alternatives, however the monetary channels linking their financial savings to such investments should be developed.
He cited the Dangote Refinery as proof that traders are keen to take part in main real-sector initiatives and earn returns from financial exercise.
The problem, subsequently, just isn’t merely encouraging folks to save lots of, however creating funding buildings that allow their financial savings to finance productive property over applicable time horizons.
This would require monetary establishments and markets to supply avenues for unusual traders to take part in main initiatives, slightly than leaving such alternatives to a comparatively small pool of traders.
His argument additionally raises a broader query in regards to the function of African pension funds and different institutional traders. These swimming pools of capital might play a higher function in financing infrastructure and productive property as an alternative of remaining closely concentrated in authorities securities.

Government borrowing and the non-public sector
A 3rd constraint is the extent to which authorities borrowing competes with non-public companies for accessible financing.
Aig-Imoukhuede acknowledged that governments have official funding necessities, however warned that public borrowing can restrict the capital accessible to companies.
He argued that central banks can not handle this problem in isolation. Collaboration amongst financial authorities, fiscal policymakers, and the non-public sector is important to realize a extra sustainable steadiness between authorities financing wants and private-sector funding.
He steered that central financial institution governors and finance ministers ought to work collectively extra intentionally on the problem.
The underlying concern is that a monetary system can stay secure whereas failing to supply adequate financing for companies able to increasing manufacturing, creating jobs and supporting financial development.
As he put it, a banking system will be secure and worthwhile however nonetheless serve an economic system that’s essentially unproductive.
African banks must compete past their house markets
Aig-Imoukhuede additionally challenged African banks to look past the rising presence of domestically owned establishments and concentrate on their potential to compete internationally.
The departure of a number of worldwide banks from African markets has created alternatives for home and regional monetary establishments. But he argued that African possession alone shouldn’t be handled as proof of progress.
“Is it enough that an international bank has exited Africa and an African bank has taken its place? No, it is not,” he mentioned.
The subsequent problem, he argued, is to translate the size of African banks into globally aggressive establishments able to serving clients throughout a number of markets.
He mentioned African banks must develop stronger regional methods and cross-border operations, whereas establishing the infrastructure wanted to attach African companies and people to the worldwide monetary system.
“We must be present in the G7 countries. We must have clearing status and establish clearing infrastructure, whether digital or through other channels, that allows African businesses and citizens to remain connected to the global economy,” he mentioned.
His feedback level to a distinction between having African-owned banks working in particular person international locations and constructing establishments able to supporting companies throughout borders and competing with worldwide monetary teams.
For Aig-Imoukhuede, the latter is the extra consequential ambition.
Financial integration can not occur with out the motion of individuals
The argument for stronger African banking establishments is carefully linked to his broader name for continental integration.
Aig-Imoukhuede mentioned the dialogue about African integration shouldn’t be restricted to the prospect of a common foreign money. Before a financial union can grow to be significant, international locations must handle the sensible limitations that prohibit the motion of products, providers, capital and folks.
He illustrated the issue together with his personal expertise on the summit. His chief of workers couldn’t journey with him to Angola as a result of he was unable to acquire a visa in time.
The expertise, he mentioned, uncovered the contradiction in discussing continental integration whereas motion between African international locations stays tough.
“We cannot build an integrated African banking industry or financial system without integrating the movement of goods, services and people,” he mentioned.
He argued that integration must precede financial union, requiring international locations to determine the sensible circumstances for companies, traders and people to function throughout borders.
That consists of functioning monetary infrastructure, simpler settlement preparations and cooperation between regulators.
Without these techniques, African banks might increase into extra international locations with out delivering the total advantages of an built-in market.
Making capital depend
Aig-Imoukhuede’s proposals finally return to at least one central situation: Africa must enhance the connection between its accessible capital and the financial actions that want it.
He referred to as for a extra productive monetary system, the combination of African monetary markets, and higher macroeconomic convergence, together with improved alignment of inflation and financial stability throughout international locations.
He additionally challenged the continent to rethink who advantages from financing main investments. The Dangote Refinery, in his illustration, shouldn’t stay an remoted instance of large-scale capital mobilisation. More Africans ought to have the ability to put money into and profit from transformative initiatives.
He framed the take a look at of progress over the following 10 to twenty years round whether or not African companies can elevate capital effectively throughout borders, whether or not pension funds could make extra significant investments in infrastructure and productive property, and whether or not the continent can lastly make its accessible capital depend.
For Africa’s monetary establishments, the implication is evident: attracting extra money is not going to, by itself, resolve the continent’s financing constraints. The higher job is to construct the techniques that allow present financial savings, industrial transactions, and institutional capital to succeed in productive companies and investments.