
In 2017, Flutterwave was an organization of about 50 folks that had satisfied Uber, the world’s largest ride-hailing firm, to belief its funds infrastructure to course of transactions throughout African markets. The firm was sufficiently small for workers to perceive what different groups had been doing and step in when wanted.
“I had just learned about a payment company that was looking to do amazing things on the continent,” Kanyinsola Ajibade, investor relations lead, who joined Flutterwave that 12 months, informed TechCabal in an interview.
Flutterwave’s story started in 2016, when its co-founder, Olugbenga “GB” Agboola, encountered an issue whereas working in monetary providers. After stints at PayPal, GTBank, a tier-one Nigerian financial institution, and South Africa’s Standard Bank, Agboola was annoyed by how tough it was for companies to transfer money throughout African markets.
“If I want to send money to Ghana, does money have to move from Lagos to New York, and from New York to Ghana?” he informed McKinsey in 2022. “It didn’t make sense to me. If you get on a plane from Lagos to Ghana, you get there faster than doing a money transfer.”
The drawback wasn’t that Africa lacked cost programs, however that these programs didn’t work seamlessly collectively. Businesses increasing throughout borders had to navigate completely different banks, cost strategies, and settlement preparations, making it tougher to acquire funds and transfer money between markets.
For a service provider in Johannesburg promoting to a buyer in Nigeria, cross-border funds meant counting on a SWIFT switch and ready for affirmation earlier than releasing the products. SWIFT messages might take up to 48 hours as they handed by correspondent banks, irritating prompt commerce. Agboola needed to make these transactions sooner and simpler.
“Those were the driving forces behind Flutterwave: How do we become like a butterfly that can create a ripple effect in the ecosystem and still be tiny, yet we can make waves? Hence the name Flutterwave, ” he informed McKinsey in 2022.
Meanwhile, Iyin Aboyeji, a co-founder of Andela, a world tech expertise community, confronted the identical drawback whereas making an attempt to help African developers and their companies and had the identical conclusion: with out funds infrastructure, promising companies would battle to develop their income.
“A lot of our talents were desirous of building products, but when I would look at the ideas they came up with, it was very clear to me that if we didn’t have payments, many of those products could not scale revenue as fast,” Aboyeji, Flutterwave’s first chief government officer, informed TechCabal in an interview.
Their ambition grew to become Flutterwave, a funds expertise firm Agboola based whereas at Access Bank, a tier-one Nigerian financial institution, with Aboyeji and Adeleke Adekoya, then Access Bank’s head of digital banking. The thought was to join retailers to banks, card networks corresponding to Visa and Mastercard, and different cost suppliers by a single Application Programming Interface (API)—a software that lets completely different apps and pc programs discuss to one another—permitting companies to acquire and disburse money with out constructing separate integrations for each market.

A decade later, Flutterwave says it has processed over $50 billion in transactions, serves more than two million businesses, and has expanded past cost processing into remittances, client funds, and banking. Aboyeji has left the corporate, and Flutterwave is now pursuing a wider financial-infrastructure technique whereas working in direction of profitability and a possible public itemizing.
Select an architectural part in the 3D area to examine it.
2016202020222026
The infrastructure drawback
In 2016, Nigeria’s digital cost infrastructure processed ₦65.16 trillion ($257.04 billion at ₦253.50/$) and included financial institution playing cards, ATMs, and the Nigeria Inter-Bank Settlement System Instant Payment service. But these rails didn’t imply companies might simply settle for funds on-line, handle failed transactions, or broaden into different African markets.
Interswitch, based in 2002, had constructed Webpay, the default cost processor for companies by 2015. But retailers confronted integration prices of ₦150,000 ($3,068.74 at ₦195.52/$); it didn’t work on cellphones, and a few startups reported transaction failure charges as excessive as 90%.
Paystack, based in 2015 and publicly launched in January 2016, emerged from this hole. It approached the issue by making on-line funds simpler for Nigerian companies to combine and handle. Flutterwave addressed a associated however broader alternative: connecting cost programs throughout nations, banks, and cost strategies so companies might settle for and settle funds throughout a number of markets.
“When we started, Africa’s payment landscape was completely fragmented. The hardest part was building an infrastructure from scratch that could securely handle transactions across totally different markets,” Agboola informed TechCabal in an e-mail response.

Flutterwave needed to construct infrastructure that related the completely different cost strategies, banks, and monetary programs companies wanted to attain prospects throughout Africa. Its JavaScript API would give retailers and cost service suppliers a standard integration by which they might settle for playing cards, financial institution transfers, and native options throughout a number of markets, slightly than construct every connection individually.
The proposition was that companies mustn’t have to perceive the underlying complexity of African funds to promote to prospects in completely different nations.
But Flutterwave nonetheless had to earn belief, and that meant proving it might transfer money quick and securely. That prompted the workforce to travel to San Francisco for a deal of a lifetime, on the time.
“Onboarding a global giant like Uber early on also helped build further trust with prospective customers. When other businesses saw that Uber trusted us to process their payments, it made choosing Flutterwave a much easier decision,” Agboola mentioned.
It wasn’t solely Uber that gave the fintech credibility. Access Bank’s PayWithCapture, a QR-code cost product launched in 2015. Both wanted technical infrastructure that related their merchandise to the cost programs prospects used.
For Uber, Flutterwave labored with Access Bank to develop an answer for native cost processing. With PayWithCapture, it had a possibility to assist a financial institution lengthen a product it had already launched however lacked the technical capability to scale.
“Pay with Capture was a very pivotal moment, as first-time clients, as well as processing for Uber,” Aboyeji mentioned. “Pay with Capture was a digital banking proposition that didn’t have the capability or technical talent to build without OTT.”
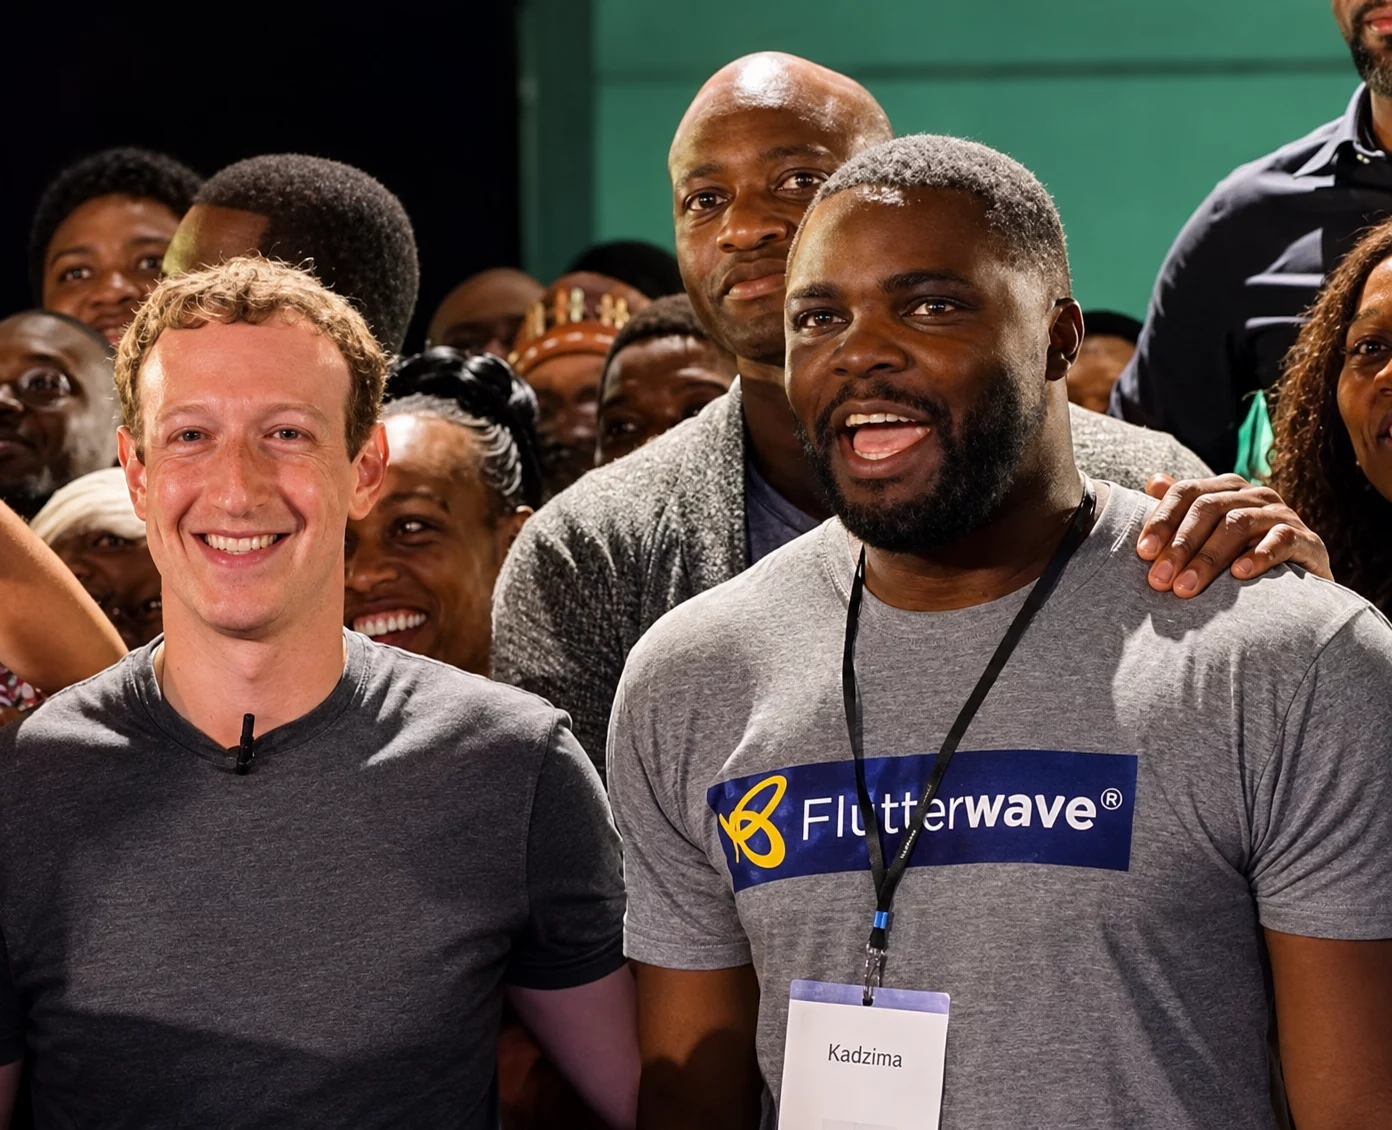
These early relationships helped Flutterwave exhibit that banks and companies might use its technical infrastructure to make their present merchandise work. They additionally provided a route right into a market the place a brand new funds firm wanted more than a working API: Access Bank supplied a connection to the banking system, whereas Uber provided a sensible check of whether or not that association might resolve a world product owner’s native funds drawback.
Building belief
Flutterwave might construct an API, however software program alone couldn’t make money transfer throughout Africa. Banks held funds, licenced establishments carried out regulated capabilities, and settlement relied on business and technical preparations that various throughout markets. Before it might supply companies an easier funds expertise, the corporate had to persuade monetary establishments to work with a younger expertise supplier and belief it with vital components of their operations.
“In payment processing, you need banking relationships because banks are licenced to hold funds, are licenced to acquire,” Temiloluwa Adesina, Flutterwave’s deputy chief product officer for retail, informed TechCabal.

Beyond convincing banks or regulators, Flutterwave had to show that it might make your entire ecosystem safer and more environment friendly. “The biggest lesson for us was that tech alone doesn’t scale on this continent; deep trust and regulatory partnerships do,” Agboola mentioned.
Its wager could not have paid off with out an early relationship with Access Bank, the place Agboola labored when Flutterwave began. Access Bank grew to become the fintech’s banking associate, and late Herbert Wigwe, the founding Group CEO of Access Holding Plc, helped the fintech pitch expertise firms in its early days.
“He was the sure reference with Silicon Valley investors and gave us business that helped us grow to become Africa’s most valuable startup,” Aboyeji mentioned in a 2024 tribute to Wigwe.
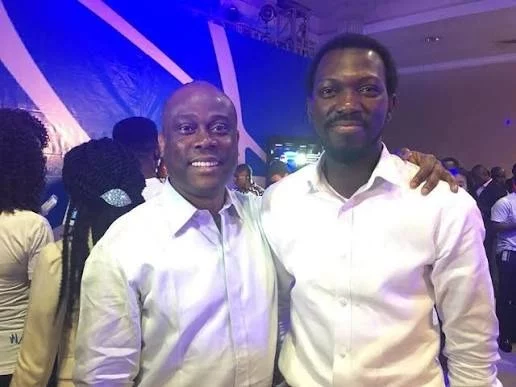
Aboyeji told TechCabal in 2022 that Access Bank needed to make investments in Flutterwave in the early days, however couldn’t due to Nigerian banking regulations that prohibited banks from getting concerned in non-banking actions.
The relationship illustrates an necessary characteristic of funds infrastructure: a brand new supplier could simplify a service provider expertise, however its service nonetheless depends on establishments that offer the underlying regulated and settlement capabilities.
“We were a young African company asking global brands and established local banks to rely on our technology,” Agboola mentioned.
Product experiments and the price of adapting
Four years after Flutterwave began, the world shut down, forcing companies to transfer on-line.
Globally, the World Bank discovered that more than 40% of adults in low- and middle-income economies who made service provider funds digitally throughout the pandemic had carried out so for the primary time. In India, more than 80 million adults made their first digital service provider cost after the beginning of the pandemic. Electronic funds rose by 49.58% in Nigeria.
The shift created an opening for payment companies, together with Flutterwave, Remita, an digital cost platform, and fintech OPay, to transfer nearer to the companies whose transactions they processed.
Flutterwave launched Flutterwave Store in 2020 to assist retailers create on-line shopfronts, show merchandise, and settle for funds whereas bodily retailers confronted restrictions. It operated in 15 African nations and related retailers to third-party logistics suppliers, together with Sendy, a logistics and supply platform, in Kenya and Sendbox, a logistics firm, in Nigeria. Flutterwave mentioned 20,000 businesses joined in its first 11 months.
“We wanted to be able to help people, small businesses, to … accept payments,” Ajibade mentioned.
The product mirrored the corporate’s view that serving to a enterprise promote on-line might create more alternatives for cost exercise. It additionally moved Flutterwave nearer to the enterprise’s day by day operations than limiting its function to the second a buyer paid. Building to match into the issue is one among Flutterwave’s core theses.
“We are customer-obsessed, close to the ground with our customers, speaking to them,” Adesina mentioned.
Within the corporate, ideation begins from market understanding: the place it’s going, and what the client wants. Its broader product historical past displays an organization making an attempt to discover the center floor between drawback identification and sustainable demand.
Rave, later often known as Flutterwave for Business, gave builders and companies entry to cost APIs. Barter provided shoppers digital greenback playing cards at a time when foreign-exchange restrictions and card-payment difficulties made worldwide spending tougher. Send App prolonged the corporate into cross-border remittances, whereas Swap was launched to assist companies and shoppers entry overseas change.
Adesina, who began at Flutterwave serving to retailers perceive its APIs, describes the corporate’s product growth course of as constructed round understanding buyer wants, learning adjoining industries, constructing shortly, and testing whether or not an answer has a sufficiently robust market.
“Once ideation happens, you need to move fast, and you need to build quickly,” he mentioned. “We move fast in terms of bringing it to life and then validating our business in the market itself.”
That strategy helps the corporate determine new income alternatives, but it surely additionally means not each product will survive when buyer behaviour, working prices, or market situations change.
Barter was discontinued in March 2024 after years of service disruptions and card rejections. Disha, a creator-storefront platform the corporate acquired in 2021, paused operations indefinitely in March 2024, requiring more than 100,000 creators to transfer their profiles and content material elsewhere.
“When you are a startup, you focus on speed and product-market fit,” Agboola mentioned. “But when you become the infrastructure that thousands of global businesses rely on to survive, your priorities change.”
Capital financed the enlargement
Capital was tough to safe in Flutterwave’s early years as a result of Interswitch was already a longtime participant in Nigeria’s digital funds business, and buyers questioned whether or not one other firm might compete.
Aboyeji lately mentioned the founders pitched hundreds of investors. Flutterwave raised a $230,000 seed spherical in August 2016, earlier than it joined Y Combinator’s Summer 2016 cohort.
“Paystack referred us to YC,” Aboyeji informed TechCabal. Paystack was the first Nigerian company to be part of the YC accelerator program.
Initially, Flutterwave had to show that it might resolve the fragmentation of African funds and that the market was massive sufficient to help the enterprise. As the corporate developed from addressing cost fragmentation to constructing a broader monetary infrastructure, investor confidence additionally grew.
“Over time, one major thing that has helped us is building on investor confidence,” mentioned Ajibade.
Flutterwave grew to become one among Africa’s fintech unicorns after elevating $170 million in a Series C spherical in March 2021, and it’s at present value more than $3 billion and has raised over $500 million.
Early capital helped Flutterwave construct its cost infrastructure, purchase prospects and set up itself in its first markets. But as the corporate proved that its mannequin might work, enlargement launched new prices: coming into extra nations required funding in native infrastructure, regulatory licences and the groups wanted to function in these markets.
Its subsequent funding rounds supported that enlargement whereas permitting it to develop and deploy new merchandise. The $35 million Series B in 2020 and $170 million Series C in 2021 got here as Flutterwave sought to lengthen its attain throughout Africa and exhibit that its cost infrastructure might be replicated throughout completely different markets. By the $250 million Series D in 2022, the corporate was explicitly allocating capital in direction of buyer acquisition, enlargement, complementary merchandise and acquisitions.
As Flutterwave matured, capital additionally grew to become a way to purchase capabilities slightly than creating each expertise in-house. Its January 2026 acquisition of open-banking startup Mono introduced financial-data entry, id verification and account-to-account cost expertise into its ecosystem. Ripple’s investment in the corporate’s June 2026 Series E spherical was tied to integrating Ripple’s stablecoin and funds infrastructure into its community.
Over the last decade, Flutterwave has additionally had to show that it may survive forex fluctuations on the continent. For occasion, in Nigeria, the naira has fallen from ₦253.50/$ in 2016 to over ₦1,300/$ in 2026.
“When you are in the African markets, you learn that you have to be resilient,” Ajibade mentioned. “You have to be able to build a strategy for macro changes that you might get into. I want to credit that to our finance and operations team, who were able to build core structures to help protect the business.”
Regulation and company governance
Flutterwave’s enlargement has introduced it into more and more complicated regulatory environments, whereas additionally exposing questions on whether or not its inside administration and governance had matured alongside its ambitions.
In April 2022, an investigation by Rest of World, the US nonprofit tech publication, documented allegations from former staff involving bullying, sexual harassment, administrative failures, and disputes over worker inventory choices. The reporting additionally raised questions on potential conflicts of curiosity involving shares that departing staff bought to Berrywood Capital, an funding car reportedly related to Agboola.
Flutterwave disputed a number of allegations, describing them as false or beforehand addressed, and mentioned it had launched insurance policies and investigated complaints.
The episode raised doubts about an organization whose business worth relied on belief: retailers relied on it to course of funds, banks relied on its expertise and controls, and buyers had dedicated capital to a enterprise anticipated to function throughout a number of monetary programs. These allegations compelled the corporate to turn into stricter with company governance.
“Governance naturally evolves as a company grows,” Flutterwave mentioned in an e-mail response to TechCabal.
Regulatory challenges quickly uncovered one other dimension of the issue. In July 2022, Kenya’s central bank mentioned Flutterwave was not authorised to present cost providers in the nation and directed regulated monetary establishments to cease coping with it.
Separately, Kenya’s Assets Recovery Agency froze funds in accounts linked to the corporate whereas investigating allegations of money laundering and fraud, which Flutterwave denied. The company subsequently withdrew its forfeiture case, and a court docket ordered the release of the frozen funds in 2024.
In September 2025, the Bank of Ghana suspended Flutterwave’s remittance partnerships for one month over breaches of its inward-remittance tips, though the corporate mentioned its different providers in Ghana remained operational.
These episodes underscored the problem of increasing a financial-services enterprise throughout jurisdictions the place licensing, settlement, and remittance guidelines differ.
The firm informed TechCabal that there is no such thing as a single strategy to constructing a world financial-services enterprise as a result of regulation and monetary infrastructure stay native.
For a funds enterprise, regulatory disputes are more than authorized bills. Regulatory restrictions can complicate banking relationships, settlement preparations, and the flexibility to serve retailers in a market. Flutterwave is exploring acquisitions to shut a few of these gaps. It is getting ready to acquire an undisclosed bank in East Africa, with Kenya, Ghana, Rwanda, Tanzania, South Africa, and Egypt strategically necessary.
“Every country has its own regulatory framework, licensing requirements, financial infrastructure, and policy priorities,” Flutterwave mentioned. “One of our biggest lessons has been that to build globally, you also have to be deeply local.”
Flutterwave says it holds more than 50 licences globally, and has made changes to its leadership and compliance capabilities because it has grown.
“As we establish and grow businesses in different countries, we have to build structures that meet local corporate governance and regulatory requirements,… while maintaining strong group standards and global best practices,” the corporate mentioned.
Flutterwave’s progress additionally uncovered it to the fraud threat of constructing a funds enterprise at scale. In October 2023, about ₦19 billion ($14.27 million) was reportedly transferred to roughly 6,000 account holders throughout 35 monetary establishments from Flutterwave.
In April 2024, TechCabal reported one other incident in which insiders estimated that ₦11 billion ($8.26 million) had been diverted, though Flutterwave mentioned no buyer funds had been misplaced or compromised. Fraud instances should not unusual to monetary establishments; banks misplaced ₦5.25 billion ($3.94 million) in Q3 2025.
The firm says it screens transactions by a 24-hour fraud desk and works with monetary establishments and regulation enforcement to examine suspicious exercise. In 2024, Flutterwave partnered with Nigeria’s Economic and Financial Crimes Commission (EFCC) to set up a cybercrime research centre. A 12 months later, it mentioned its security measures included encryption, tokenisation and multi-factor authentication to defend prospects towards fraud.
The lengthy stroll to profitability
Flutterwave’s scale has not translated into earnings.
The firm says it has processed over $50 billion throughout one billion transactions, however transaction worth shouldn’t be the identical as income, and income shouldn’t be the identical as revenue. Payment processors earn a fraction of the worth they course of, whereas carrying the prices of expertise, buyer help, compliance, fraud prevention, native operations, and relationships with monetary establishments.
Agboola identified profitability and operational efficiency as priorities in 2025, forward of a possible public itemizing. In July 2026, he informed The Africa Report that Flutterwave was working in direction of profitability and would take into account going public after reaching that milestone.
Now, the corporate’s technique more and more includes shifting nearer to the underlying monetary infrastructure. In 2022, Flutterwave acquired a switching and processing licence from the Central Bank of Nigeria, permitting it to carry out capabilities in the funds worth chain that beforehand relied on different licenced establishments.
Its January acquisition of open banking startup Mono brought a Nigerian microfinance banking licence into its ecosystem, making a route to maintain deposits and develop banking providers inside the scope of that licence.
Controlling more of the transaction lifecycle might scale back dependence on third events, enhance settlement and create new earnings sources. Agboola informed TechCabal in April that the corporate’s new section would keep funds on its platform, enhancing margins.
Incremental Annual Value
+$4.0M
Owned rails generate $4.0M more working revenue yearly than exterior rails. Break-even on fastened overhead ($20M) is reached at 33% inside routing share.
Assumptions & Methodology
Fixed Operating Overhead: Baseline working bills are pegged at $35M. Transitioning to an owned infrastructure mannequin introduces an estimated $20M in ongoing regulatory, compliance, and core switching upkeep overhead.
Variable Rails Routing: In the ‘External’ mannequin, 100% of cost quantity is topic to exterior associate charges. Under the ‘Owned’ mannequin, processed quantity is cut up between decrease inside routing prices and associate clearing.
Editorial Note: Built per The TechCabal Way[cite: 1] as an editorial explainer to reveal structural unit economics[cite: 6, 12], slightly than an official monetary projection of any single operator.
A banking enterprise provides Flutterwave entry to deposits and curiosity earnings, whereas transaction information helps it assess the wants and reimbursement capability of small companies in search of working capital, bill discounting or commerce finance.
Its current partnerships round stablecoins and blockchain-based settlement level to an analogous curiosity in discovering new methods to transfer worth throughout monetary programs that stay tough to join. Flutterwave’s mission stays connecting Africa to the world by funds, however the sensible which means of that ambition has widened significantly.
“In 2016, we set out with the mission to solve payment fragmentation across Africa,” Agboola mentioned. “Flutterwave is much larger than a payment gateway now; we are building the continent’s financial infrastructure…. The mission hasn’t changed; we are still connecting Africa to the world, but our capacity to drive global commerce has scaled.”