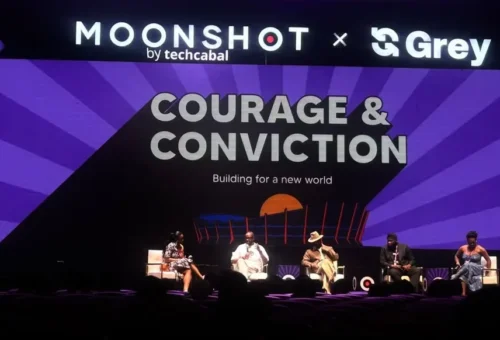
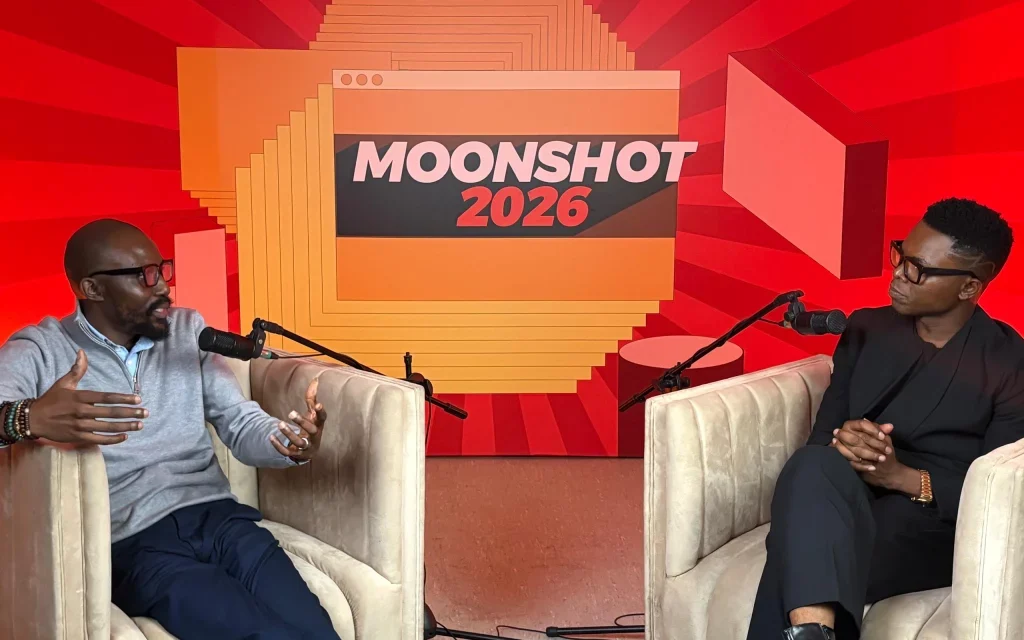
Interswitch, a Nigerian funds expertise firm, says shopper training is the most important hurdle to making tap-to-pay a mainstream fee methodology in Nigeria, whilst banks and retailers put together to assist it. Speaking at Moonshot 2026 in Lagos on Thursday, Tomi Ogunlesi, divisional head of manufacturers, communication, content material and CSR at Interswitch, stated the trade should persuade customers that tapping their playing cards or telephones to pay is safe and handy.
“The banks are ready,” Ogunlesi stated. “Where more of the work needs to be done now, from our perspective as an industry, is on the merchant side and on the consumer side, but most on the consumer side.”
His feedback come after Mastercard and Interswitch announced the launch of Google Pay in Nigeria, permitting eligible Mastercard holders to add their playing cards to Google Wallet and pay with suitable Android telephones at contactless-enabled terminals. Interswitch’ stated that it was working with 5 Nigerian banks, together with GTBank, Wema Bank, ProvidusUnity Bank, Zenith Bank, and FirstBank, to develop tokenised tap-to-pay transactions. The firm stated it’s also working to deliver extra retailers into the community, together with grocery store chain, Spar, had proven curiosity.
Contactless funds are usually not new to Nigeria. In 2015, Unified Payments launched PayAttitude, an NFC-based fee service, with a number of Nigerian banks. It used a chip-enabled tag hooked up to a cell phone or one other floor to make funds at suitable terminals.
A decade later, Access Bank partnered with Visa in March 2025 to launch Tap to Phone, which turns an NFC-enabled Android smartphone right into a fee terminal for retailers accepting contactless card funds. In October, CashAfrica, a Nigerian contactless funds infrastructure startup, additionally partnered with Chicken Republic to deliver cellular tap-to-pay to greater than 350 shops.
Despite these makes an attempt, tap-to-pay has but to turn into a mainstream fee methodology in Nigeria. Infrastructure gaps and restricted shopper consciousness have made it tough for contactless funds to acquire widespread adoption. Interswitch has now taken up the problem to persuade customers to use the expertise.
Ogunlesi stated Interswitch had anticipated the shift in the direction of tokenised funds by making many of the playing cards it issued over the previous two to three years suitable with the expertise. However, he acknowledged that the simplicity of tap-to-pay may itself make some Nigerians suspicious. Ogunlesi stated shopper training should clarify how tokenisation protects fee particulars.
“At its core, tokenisation means your card details have gone through a process where the token that is replacing your card number in a tap-to-pay transaction is not your card number,” he stated. “It’s more like a one-time token that is being used to mask your card number.”
Interswitch plans to assist sensitisation efforts with a 15-minute documentary titled ‘Are You Tapping?,‘ which explores the evolution of funds in Nigeria and explains why tokenisation issues.
In a separate dialog at Moonshot, Ogunlesi stated Nigeria embraced card funds sooner than another African markets, the place cellular cash providers helped drive the expansion of digital funds. He pointed to Interswitch’s expertise in 2009, when the Central Bank of Nigeria ordered the shutdown of magnetic-stripe playing cards amid fraud considerations. It compelled the trade to transition in the direction of EMV chip playing cards, creating a chance for Verve, Interswitch’s home card scheme.
He additionally argued that playing cards retain a bonus in areas corresponding to worldwide commerce and dispute decision, the place established card networks have developed processes for dealing with failed transactions and recovering funds. Bank transfers may go properly for home funds, however resolving disputes involving cross-border transactions may be extra sophisticated. He expects the bodily type of playing cards to change as funds turn into digital, however believes the underlying infrastructure will stay essential.
“Cards are what everybody is trying to disrupt,” he stated. “But the interesting thing is that even the things that are going to disrupt cards run with the DNA of cards.”
Ogunlesi recognized card rails, non-card rails corresponding to on the spot financial institution transfers, and digital-asset rails as three broad areas of fee infrastructure that might assist sooner or cheaper cross-border transfers. He stated Interswitch was exploring how digital-asset infrastructure might be developed in methods which might be trusted and suitable with regulatory necessities. However, the corporate’s fast precedence is getting extra Nigerians snug with tapping to pay.