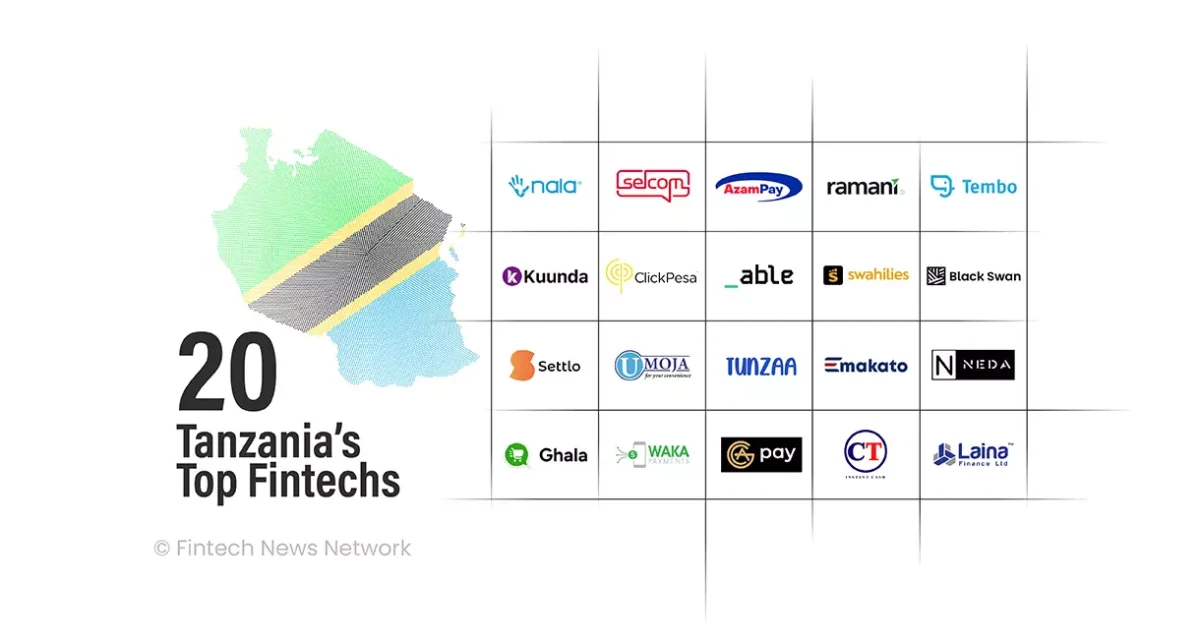

First, I requested Linkedin for names to be added to the top 20, Tanzania’s fintech story is normally informed via cellular cash.
That is comprehensible. Mobile cash modified the nation. It introduced thousands and thousands of individuals into the formal monetary system, made on a regular basis funds simpler, and created the rails for a extra digital financial system led by lending, betting and retailers funds.
The remainder of the chapters on this e-book are being written by impartial fintech firms constructing funds infrastructure, service provider instruments, embedded finance, cross-border funds, credit score scoring, switching, stablecoins, enterprise funds, SME working programs, recurring collections, digital lending and monetary APIs.
I need to warn you that This article isn’t an inventory of each fintech product working in Tanzania. It is an inventory of impartial, Tanzania led, Tanzania first fintech firms. That means M-Pesa, AirtelCash, PalmPay and SasaPay are excluded by design. Not as a result of they’re unimportant. They’re crucial however my objective was to create house to showcase what I think about to be actually “Tanzania’s Fintech”.
The left outs giants performed an enormous function in increasing monetary entry. Their exclusion is solely a matter of scope. Because this text is targeted on a special query:
Which fintech firms are being constructed from Tanzania (eg Ramani, Tembo, Selcom) or received their first significant crack of the market in Tanzania (eg Nala, Kuunda), not merely which fintech merchandise function in Tanzania?
The reply is extra fascinating than many individuals suppose. Tanzania now has fintech firms working throughout remittances, fee gateways, service provider programs, SME finance, switching, liquidity, stablecoins, direct debit, cross-border funds, credit score scoring, shopper finance and digital commerce infrastructure.
Tanzanian Top fintechs are backed by a mixture of native and international buyers, together with Hustle Fund, Y Combinator, DeveloPPP and Warioba Ventures. Together, they’re serving to flip a fintech adoption market right into a fintech -building market.
The Top Twenters present that Tanzania’s fintech is now not nearly utilizing know-how constructed elsewhere. It is more and more about constructing the know-how ourselves.
Here is the listing of Tanzania’s Top 20 Fintechs as curated by Reuben Mwatosya of Cofounders Notebook and His Linkedin Community.
NALA is Tanzania’s most globally recognised fintech. What started as a Tanzanian-born remittance firm has grown into a global funds enterprise serving Africans throughout the UK, US, Europe and a number of African markets. Its shopper product helps the diaspora ship cash residence, whereas its broader infrastructure play, Rafiki, factors to an even bigger ambition: constructing fee rails for rising markets.
NALA issues as a result of it has modified what Tanzanian startups consider is feasible.It has proven that an organization with Tanzanian roots can increase critical worldwide capital, construct for international markets and compete in one of many hardest classes in fintech: cross-border funds.
Its focus space is obvious: remittances, cross-border funds and worldwide fee infrastructure. For Tanzania, NALA is greater than a fintech success story. It is a sign that regionally rooted firms can construct for the world.
Selcom is one in every of Tanzania’s authentic fintech infrastructure firms.Long earlier than fintech grew to become a modern phrase, Selcom was already serving to companies, banks, billers, brokers and retailers course of digital funds. Its infrastructure has supported invoice funds, service provider funds, company banking, collections, disbursements and integrations throughout the monetary ecosystem.
Selcom’s significance is not only that it exists. It is that it has endured and carried each financial institution, cellular cash and lots of fintechs that got here after. In a market the place many fintech startups come and go, Selcom has remained on the centre of Tanzania’s digital funds spine for years, and it powered switching for years earlier than the nationwide swap.
Its focus space is funds infrastructure, service provider companies, collections and digital transaction processing. Infrastructure isn’t glamorous, however it’s foundational. That is why Selcom belongs close to the highest of this listing.
Unlike many VC backed startups, AzamPay is backed by the Bakhresa ecosystem, AzamPay serves companies that want dependable methods to gather funds, automate transactions, reconcile collections and connect with digital fee channels.
They are the one non telco cellular cash operator and Its significance comes from execution at a posh scale of a conglomerate. Tanzania’s enterprise financial system continues to be closely cash-based. Companies that make digital funds simpler for retailers, corporates and establishments are central to the nation’s subsequent monetary transformation.
AzamPay’s focus space is service provider funds, cellular cash and digital commerce infrastructure. Its profile has additionally moved past Tanzania, with global recognition serving to place it as one of many nation’s most seen fee infrastructure firms.
Ramani sits on the intersection of provide chain, information and embedded finance. The firm digitises micro-distribution and shopper items provide chains, serving to distributors, manufacturers and retailers perceive gross sales, stock and money circulation extra clearly. That working information can then change into the muse for credit score and dealing capital.
Ramani is essential as a result of it reveals one of the crucial highly effective instructions in African fintech: finance embedded inside actual commerce. Instead of asking small companies to stroll right into a financial institution with restricted data, Ramani helps create the data first.
That makes retailers extra seen, extra measurable and extra financeable. Its focus space is supply-chain finance, service provider information, working capital and embedded finance.
TemboPlus is constructing fee and banking infrastructure for companies. Its API-led mannequin helps firms embed monetary companies into their very own merchandise. That consists of funds, collections, wallets, accounts, cellular cash integrations, remittances and different monetary infrastructure.
TemboPlus issues as a result of the subsequent wave of fintech won’t solely be about standalone shopper apps. It may also be about infrastructure that permits different firms to launch monetary companies sooner.
Every market, logistics firm, lender, service provider system, college platform, subscription firm or enterprise software program product might ultimately want embedded funds or monetary options. Tembo is constructing for that world.
Kuunda is among the most essential embedded liquidity fintechs linked to Tanzania greatest credit score product (Songesha on Mpesa). Its mannequin focuses on short-term liquidity merchandise comparable to cellular cash float loans, airtime float, service provider money advances, inventory financing and working-capital options.
These merchandise resolve a really actual drawback in African commerce: brokers and retailers usually lose transactions as a result of they run out of float or working capital.Kuunda’s energy is that it embeds credit score the place transactions already occur.
Rather than forcing clients right into a separate lending journey, it locations liquidity contained in the platforms and channels retailers already use.
Probably the second oldest Fintech after Selcom, Click onPesa is a enterprise funds platform targeted on serving to firms handle funds extra effectively, plus they had been very early in crypto and issued the first TZS stablecoin on stellar.
Its core merchandise serve SMEs, corporates, MFIs and organisations that have to deal with collections, payouts, fee automation and reconciliation throughout a number of channels.
Click onPesa belongs on this listing as a result of enterprise funds are nonetheless one of many least glamorous however most essential they write about the challenges and opportunities
With strong partnership w DTB, Airtel and Vodacom, Credable is an embedded finance and digital banking infrastructure firm with robust Tanzanian roots.
It works with banks, telecoms and companies to launch credit score and financial savings merchandise via current buyer channels. Credable issues as a result of distribution is among the hardest issues in monetary companies.
Instead of attempting to amass each buyer instantly, Credable allows establishments and platforms that have already got clients to supply monetary merchandise. Its focus space is embedded finance, digital banking infrastructure and credit score enablement.
Swahilies is among the strongest SME-focused fintech firms in Tanzania. It gives a monetary working system for small companies, combining instruments for stock, gross sales, funds, analytics and enterprise operations.
Its give attention to SMEs is essential as a result of Tanzania’s financial system is constructed on small and casual companies that always lack clear data, structured fee histories and entry to formal finance.
Swahilies issues as a result of SME digitisation is a fintech drawback NOT a software program drawback. Once a small enterprise has digital data, it turns into simpler to supply funds, working capital, financial savings, insurance coverage and different monetary companies.
Its focus space is SME working programs, enterprise administration, funds and service provider information. Swahilies is greater than a enterprise software. It is a part of the info layer for SME finance together with cross border funds, credit score and native funds.
Black Swan is an AI-driven fintech targeted on different credit score scoring and monetary inclusion not too long ago recognised by Bloomberg.
Its work is essential as a result of Tanzania, like many African markets, nonetheless has a serious credit score info hole. Many people and small companies are economically lively however invisible to conventional lenders as a result of they lack formal credit score histories.
Black Swan addresses that hole by utilizing different information and AI-driven scoring to assist lenders perceive danger extra successfully.
Its momentum has additionally obtained continental recognition, with Black Swan named amongst African startups to observe. Its focus space is different credit score scoring, consent-based monetary information sharing, lending intelligence and monetary inclusion.
UmojaSwitch is one in every of Tanzania’s most essential monetary infrastructure gamers. It gives shared digital fee and fund-transfer infrastructure that connects banks and different financial-service suppliers. Its function is probably not as seen as a shopper app, however it’s deeply essential.
A monetary ecosystem wants switches, rails and interoperability. Without these layers, banks, retailers, ATMs, playing cards and suppliers can’t join effectively.
Its focus space is switching, interoperability, fee infrastructure and monetary connectivity. UmojaSwitch belongs on this listing as a result of fintech isn’t solely concerning the firms customers see. It can be concerning the infrastructure that makes transactions doable behind the scenes.
Tunzaa sits within the shopper finance and save-to-buy class. Its mannequin helps clients plan purchases, save towards merchandise and entry items in a extra structured approach. This issues as a result of many customers can’t afford massive purchases upfront, but in addition don’t wish to fall into irresponsible debt. The save-now-buy-later mannequin is a crucial different to pure lending.
Tunzaa’s focus space is shopper finance, structured financial savings, affordability and commerce. It belongs on this listing as a result of Tanzania wants extra fintech merchandise that assist folks plan, save and purchase responsibly.In markets with irregular revenue, affordability is not only about credit score. It can be about self-discipline, timing and construction.
Cofounded and led by the cofounder of Laina Finance, SoloCodes is constructing E-makato, a direct debit resolution for recurring subscriber and utility funds.
This is a crucial fintech class as a result of many companies in Tanzania nonetheless wrestle with recurring collections. Subscriptions, college charges, insurance coverage premiums, hire, utilities, mortgage repayments and repair payments usually rely upon guide follow-ups, cellular cash prompts or irregular customer-initiated funds.
E-makato addresses that hole by serving to companies acquire recurring funds extra predictably. Direct debit infrastructure might not sound as thrilling as shopper apps or remittances, nevertheless it is among the final lacking layers in Tanzania’s fee ecosystem.
The firm is constructing nTZS, a Tanzanian shilling-pegged stablecoin. This locations it on the frontier of managed experimentation with blockchain-based funds and digital property within the nation.
In rising markets, regulated digital cash may probably help sooner settlement, programmable funds, cross-border and new monetary infrastructure.
NEDA Labs belongs on this listing as a result of it’s pushing the boundary of what fintech regulation and innovation can seem like, that’s larger than stablecoin as a class.
Its inclusion issues as a result of Tanzania’s fintech ecosystem is now not restricted to fee gateways and cellular cash integrations. The ecosystem is starting to incorporate extra superior infrastructure, regulated experimentation and know-how merchandise that may help monetary companies in new methods.
Ghala’s focus space is monetary infrastructure, sandbox innovation and digital monetary know-how. The significance of merchandise like Ghala isn’t solely what they do as we speak. It is what they sign. They present that founders are starting to construct for regulated monetary innovation from the beginning, not as an afterthought. That is a wholesome signal for the market.
WakaPay is an outward cross-border funds platform targeted on serving to customers and companies make funds throughout African markets.
Its mannequin is very related as a result of Tanzania is deeply related to regional commerce, diaspora motion and cross-border commerce. Tanzanian customers, Kenyan retailers, regional merchants and cellular cash customers usually want sooner and less complicated methods to maneuver worth throughout borders.
WakaPay’s focus space is cross-border cellular cash, service provider funds and intra-African commerce. This is among the greatest alternatives in African fintech. Trade already strikes throughout borders. People already transfer throughout borders. Families already transfer cash throughout borders.
Recently licensed GCA Pay is among the Old fintech firms in Tanzania by volumes and worth they deal with. Built beneath Goldcavern Associates, it sits on the intersection of FX, cross-border settlement and enterprise monetary infrastructure.
Its positioning is essential as a result of Tanzania is more and more turning into a settlement and commerce hall market, particularly for companies shifting cash between Africa, Asia and different international markets. Companies don’t solely want fee assortment. They want liquidity, compliance, FX, reconciliation and dependable settlement throughout a number of rails.
Its focus space is cross-border funds, treasury, FX, provider funds, collections, payouts and enterprise settlement infrastructure. GCA Pay is greater than a fee gateway. It is a part of the infrastructure layer for African commerce, stablecoin-powered settlement and regional enterprise funds.
Powered by crowdfunding, CashMe Tanzania represents the digital credit score and short-term finance facet of the ecosystem. Credit stays one of many greatest gaps in Tanzania’s monetary system. Many folks and small companies want entry to quick, versatile and accountable financing, however conventional channels will be gradual, paperwork-heavy or inaccessible.
CashMe Tanzania’s focus space is digital lending and crowdfunding which is area of interest however fascinating sufficient to showcase what is feasible at scale. Digital lending can create actual worth when it’s clear, truthful and accountable.
Probably the OG of smartphone lending in Tanzania, Laina Finance focuses on digital lending and versatile financing for Tanzanian customers and companies.
Its inclusion is essential as a result of credit score entry stays one of many greatest gaps in Tanzania’s monetary system and Laina was one of many pioneers within the house. Laina represents the digital credit score layer of the ecosystem. Its focus space is digital lending, instalment finance and versatile shopper or enterprise financing.
This class is central to fintech as a result of funds alone don’t resolve monetary inclusion. People and companies additionally want higher methods to entry capital, easy revenue gaps and finance helpful property.
Tanzania’s fintech ecosystem isn’t but as massive or globally seen as Kenya or South Africa. But it’s extra fascinating than many individuals realise. This listing reveals a market shifting past the primary layer of cellular cash right into a broader fintech stack:
Remittances, funds infrastructure, service provider instruments, embedded finance, switching, credit score scoring, SME working programs, enterprise funds, stablecoins, direct debit, cross-border funds, digital lending, shopper finance and controlled sandbox innovation.That is a a lot richer story. The first wave of Tanzania’s digital finance was constructed by telcos, banks and huge fee operators.
The subsequent wave is being constructed by fintech entrepreneurs, infrastructure firms and embedded-finance platforms that perceive native issues deeply. And essentially the most thrilling half is that many essential classes are nonetheless vast open.
Tanzania wants extra firms constructing recurring fee infrastructure. Subscriptions, insurance coverage premiums, college charges, hire, utilities, mortgage repayments and enterprise memberships mustn’t rely solely on guide reminders or customer-initiated funds.
Reliable direct debit infrastructure can unlock subscription companies, scale back assortment prices and assist service suppliers plan money circulation higher. This is among the least glamorous however most essential fintech gaps.
Small companies energy Tanzania’s financial system, however many nonetheless lack entry to quick, truthful and versatile credit score. The alternative isn’t solely to lend. It is to construct higher underwriting fashions utilizing gross sales information, stock information, funds information, provider relationships and transaction historical past. The subsequent era of SME lenders won’t win by copying outdated banking fashions. They will win by understanding actual enterprise behaviour.
Many retailers nonetheless function in cash-heavy environments. Tanzania wants extra innovation in service provider buying, QR funds, low-cost acceptance, offline funds, reconciliation and settlement. The objective mustn’t merely be to digitise transactions. The objective ought to be to make digital funds simpler than money.
Tanzania sits in a area the place commerce, journey and household networks cross borders each day. Yet cross-border funds stay too gradual, too costly or too difficult for many individuals and small companies. There is room for extra gamers constructing regional fee rails between Tanzania, Kenya, Uganda, Rwanda, Zambia, Malawi, DRC and past.
Insurance penetration stays low, however the want is big. Health, crop, asset, funeral, motor and microinsurance merchandise can change into extra accessible if distribution, pricing, claims and funds are digitised correctly. Tanzania wants extra insurtech gamers that may make insurance coverage easy, reasonably priced and trusted.
As digital finance grows, so do fraud, compliance and id challenges. Tanzania wants extra fintech infrastructure round KYC, KYB, fraud detection, transaction monitoring, consent-based information sharing and safe id verification. These merchandise might not at all times be seen to customers, however they’re important for belief. Without belief, fintech can’t scale.
The way forward for credit score, financial savings, insurance coverage and personalised monetary companies will rely upon higher information portability and user-controlled monetary information. Tanzania wants extra gamers constructing the rails for protected, permissioned and controlled monetary information sharing. This may assist lenders make higher selections, assist clients entry higher merchandise, and assist monetary establishments serve customers extra intelligently.
The way forward for Tanzanian fintech won’t be gained by one firm. It shall be constructed layer by layer. One firm will construct cross-border rails. Another will construct service provider programs. Another will construct direct debit. Another will construct credit score scoring. Another will construct stablecoin settlement.
Another will digitise SMEs. Another will join banks, wallets and companies behind the scenes. That is how ecosystems are constructed. Not via one tremendous app. But via many specialised firms fixing arduous, particular issues.
Tanzania already has the primary era of significant fintech builders. The subsequent query is whether or not the nation can produce the subsequent 50. Because the chance isn’t small. It is huge. Tanzania doesn’t simply have to undertake fintech. Tanzania can construct fintech.
This article first appeared on https://reubenmars.substack.com/
Featured picture: Edited by Fintech News Africa, primarily based on picture by graphic_titan through Magnific
(*20*)